eCheck Payment Processing Services for Businesses!
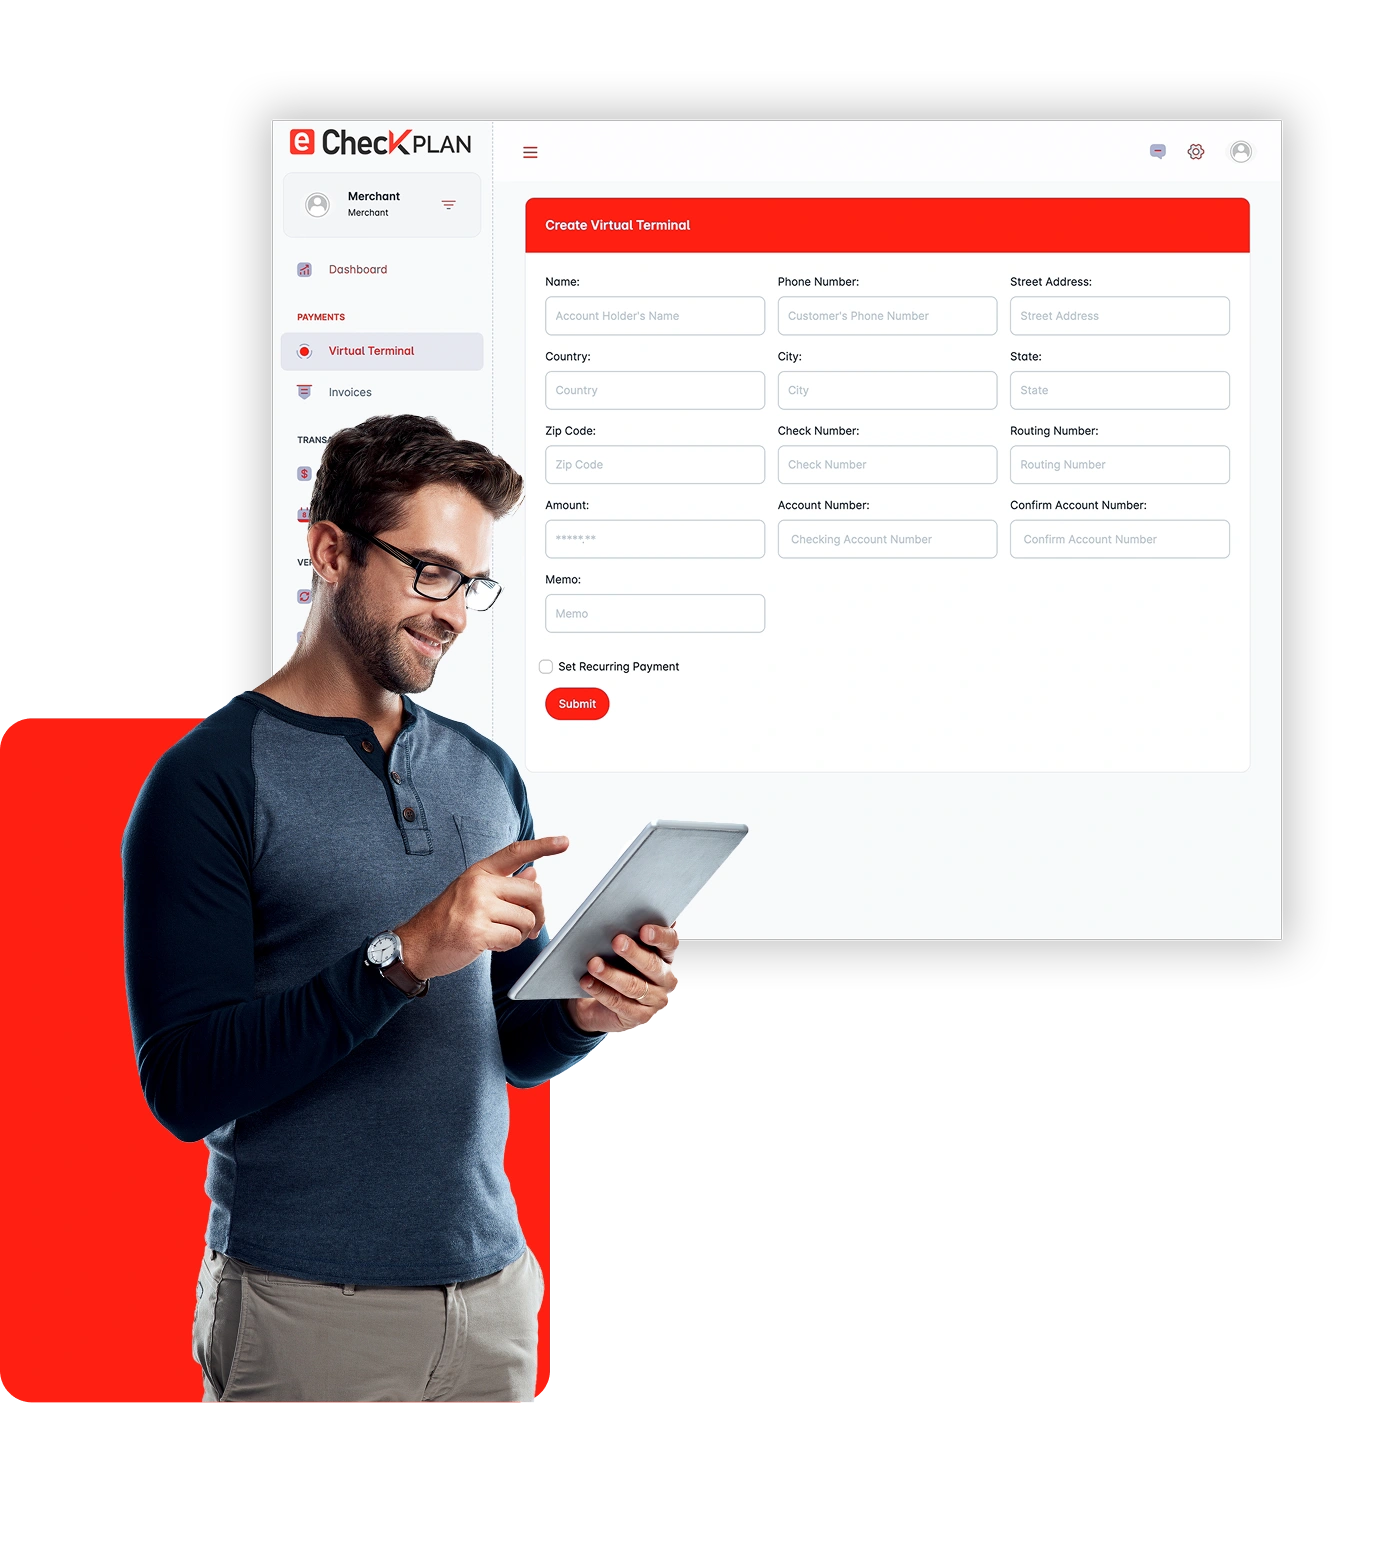
Traditional card processing works well for many transactions. But for certain business models, it creates real friction — from surprise declines on large orders to fees that quietly erode margins.
For businesses that process high-ticket transactions, run recurring billing, or have seen a steady rise in declines, eCheck is worth a serious look.
eCheck payments pull funds directly from a verified bank account. There are no card networks involved — which means fewer declines, no card expiration issues, and significantly lower processing costs.
For recurring billing, subscriptions, B2B invoicing, and large-ticket sales, eCheck is often the more practical and cost-effective payment method.
An eCheck — or electronic check — is a digital version of a paper check. Instead of writing a check and waiting for it to clear physically, an eCheck transmits payment instructions electronically through the ACH (Automated Clearing House) network directly between bank accounts.
For businesses, this means accepting payments without needing a card on file. The customer provides their bank routing and account number, and the payment is authorized, processed, and settled — typically within one to three business days.
eCheck processing is widely used for invoicing, subscription billing, high-value B2B transactions, and situations where card acceptance isn't practical or cost-effective.
Secure authorization is captured.
Bank details are verified and stored.
Payment enters the ACH network.
Funds settle into your account.
eCheck payments offer several operational and financial advantages for businesses:
Processing fees are typically lower than credit card payments, making it ideal for high-volume or high-value transactions.
Bank-based payments bypass the frequent decline issues often experienced with card transactions.
eCheck payments have fewer disputes compared to card payments, helping businesses minimize revenue loss.
Large payments can be processed more efficiently without the limitations commonly associated with card networks.
Smarter Payments.
Stronger Business.
A structured transaction flow improves reliability and reduces payment failures.
| Factor | eCheck (ACH) | Credit Card |
|---|---|---|
| Transaction Fees | Low flat rate (ACH) | 1.5%–3.5%+ per transaction |
| High-Ticket Approval | Strong — bank-level approval | Frequent declines above limits |
| Chargeback Risk | Lower — different dispute process | Higher exposure to disputes |
| Recurring Billing | Uninterrupted — no expiration | Fails when cards expire or change |
| Settlement Speed | 1–3 business days | 1–2 business days |
| B2B Acceptance | Preferred by many businesses | Varies by client preference |
| High-Risk Eligibility | More accessible for high-risk | Limited options for high-risk |
| Setup Requirements | Bank account and authorization | Card on file required |
Card-based payments carry a structural problem for recurring and high-ticket billing: they depend on something that changes — card numbers, expiration dates, and issuer approval rules. Each change is a potential failure point.
eCheck payments are tied to bank accounts, which are far more stable. A business checking account stays active for years. Routing and account numbers don't expire, and ACH authorization doesn't run through the same approval logic that causes card declines.
For businesses that rely on consistent cash flow, this stability matters. Fewer failed payments mean less time spent chasing customers, re-running transactions, and handling failed-billing notifications.
eCheckPlan also includes bank account verification before processing, which screens out inactive or invalid accounts before a transaction is attempted — reducing returns and NSF failures at the source.
ACH bypasses card-issuer approval, so transactions that fail on cards often go through as eChecks.
Bank accounts don't expire. Recurring billing continues without card-replacement interruptions.
Account validation before processing reduces returns and protects your processing history.
Predictable settlement timelines help you plan operations and manage working capital.
eCheck payment processing is widely used across different business models, including:
Fast online application.
Quick onboarding.
Login to your dashboard.
Start getting paid.
Speak with our team to understand how eCheck payment processing fits your business model. We’ll help you evaluate costs, approval rates, and the best setup for your transactions.
Talk to an ExpertA reliable way to process payments with better cost control, fewer limitations, and improved transaction consistency.